Four ways to buy the same home
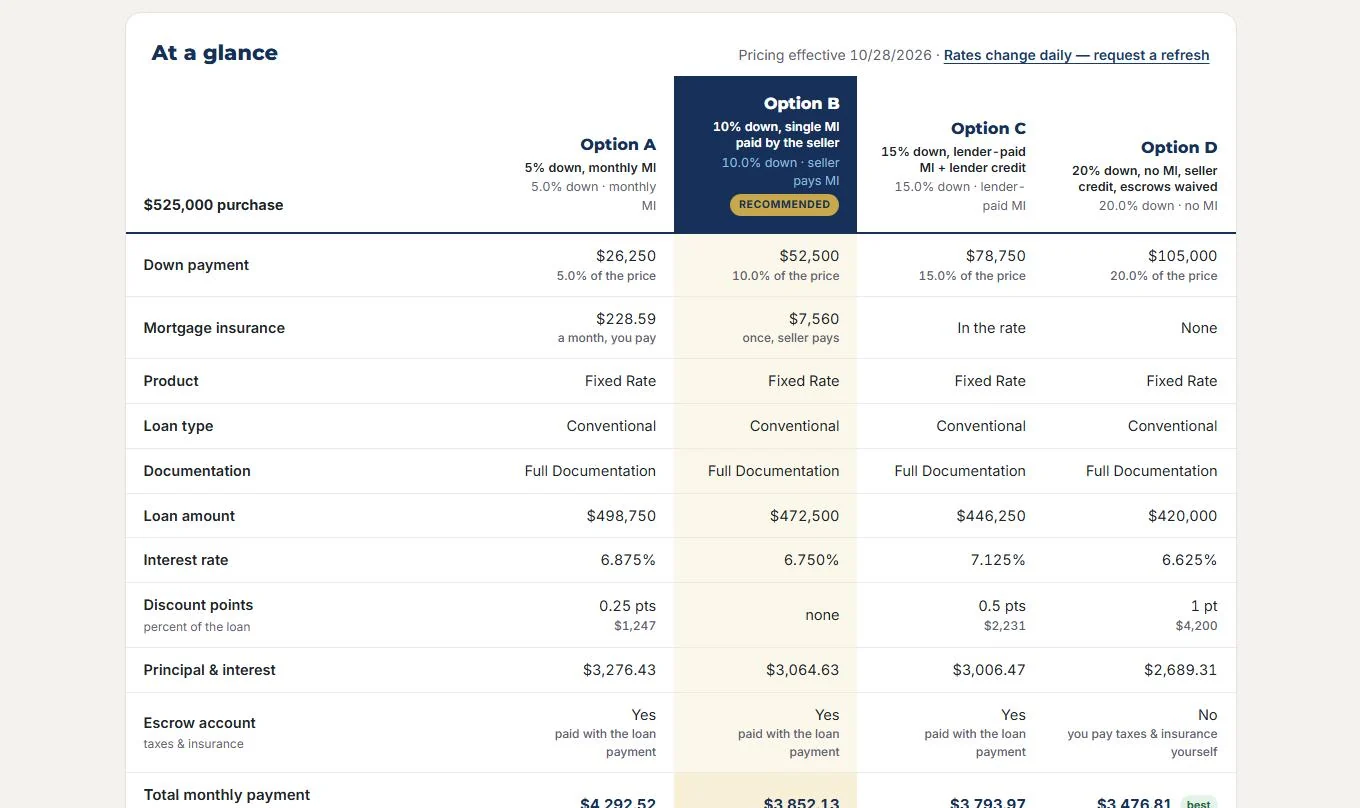
Different down payments and ways of handling mortgage insurance, compared on the cash you need, the payment and the long-term cost.

See what you get at each step: a Total Cost Analysis that compares your options line by line, a pre-approval our underwriter has verified, an update by email and text at every milestone, and a live portal for your real estate agent. Every example on this page is a real Fidelity Residential page or message, made for fictional clients.
Prefer to talk? Call 732-686-9999
Fidelity Residential · NMLS #103098 · Equal Housing Lender
Every quote we send is a personal web page that puts your options side by side: the monthly payment, the closing costs, the cash you need at closing, and what each option costs you over five years and over the life of the loan. It names the option we would choose and why, then shows every figure behind it, itemized the way a Loan Estimate is. It works on any phone or computer, and you can call, text or email your loan officer, request updated pricing, run what-if numbers or print it from the page.
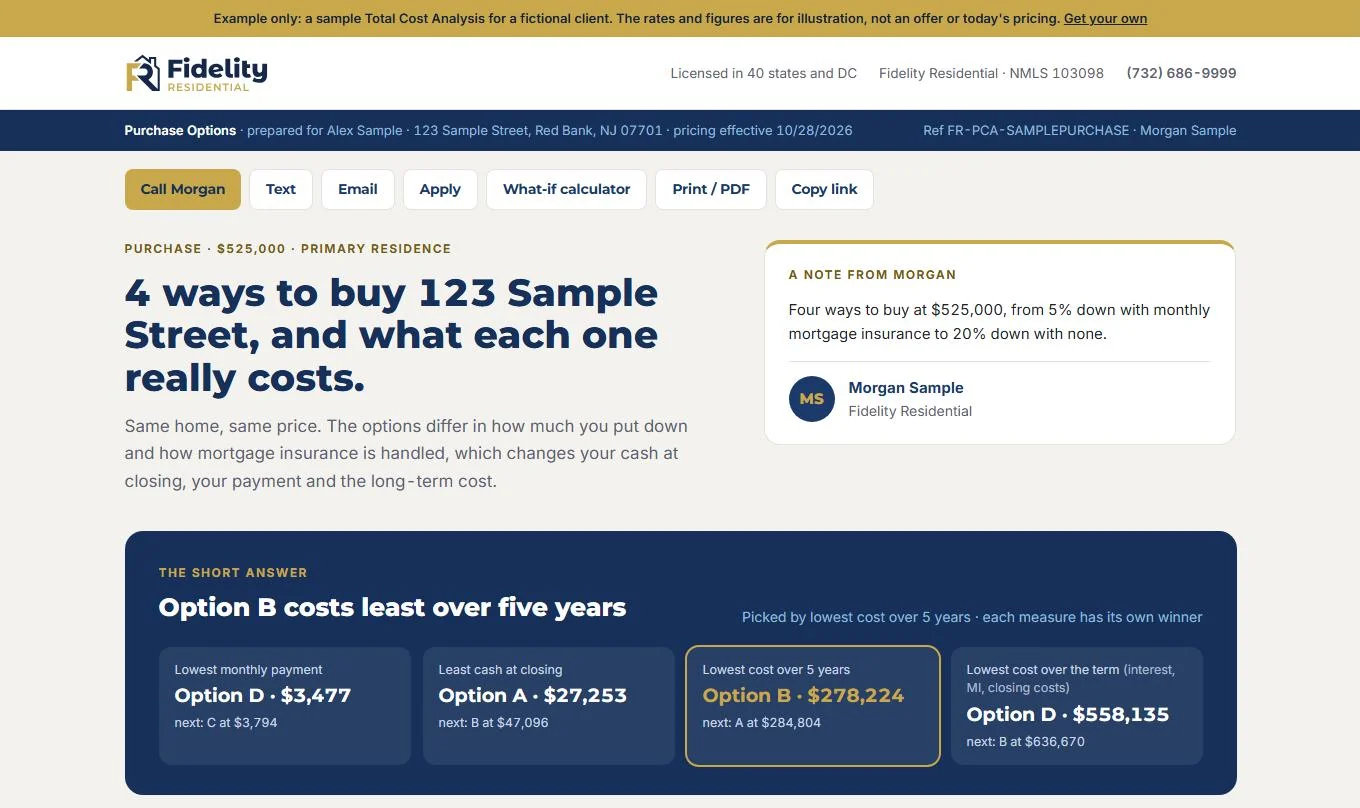
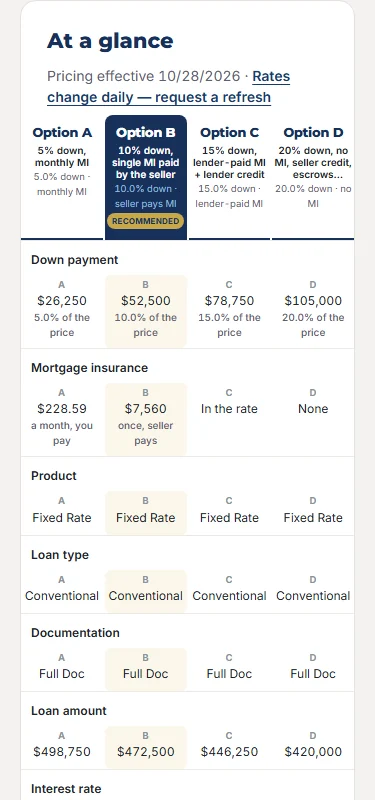
On a phone, all the options still sit side by side, row by row.
Different down payments and ways of handling mortgage insurance, compared on the cash you need, the payment and the long-term cost.
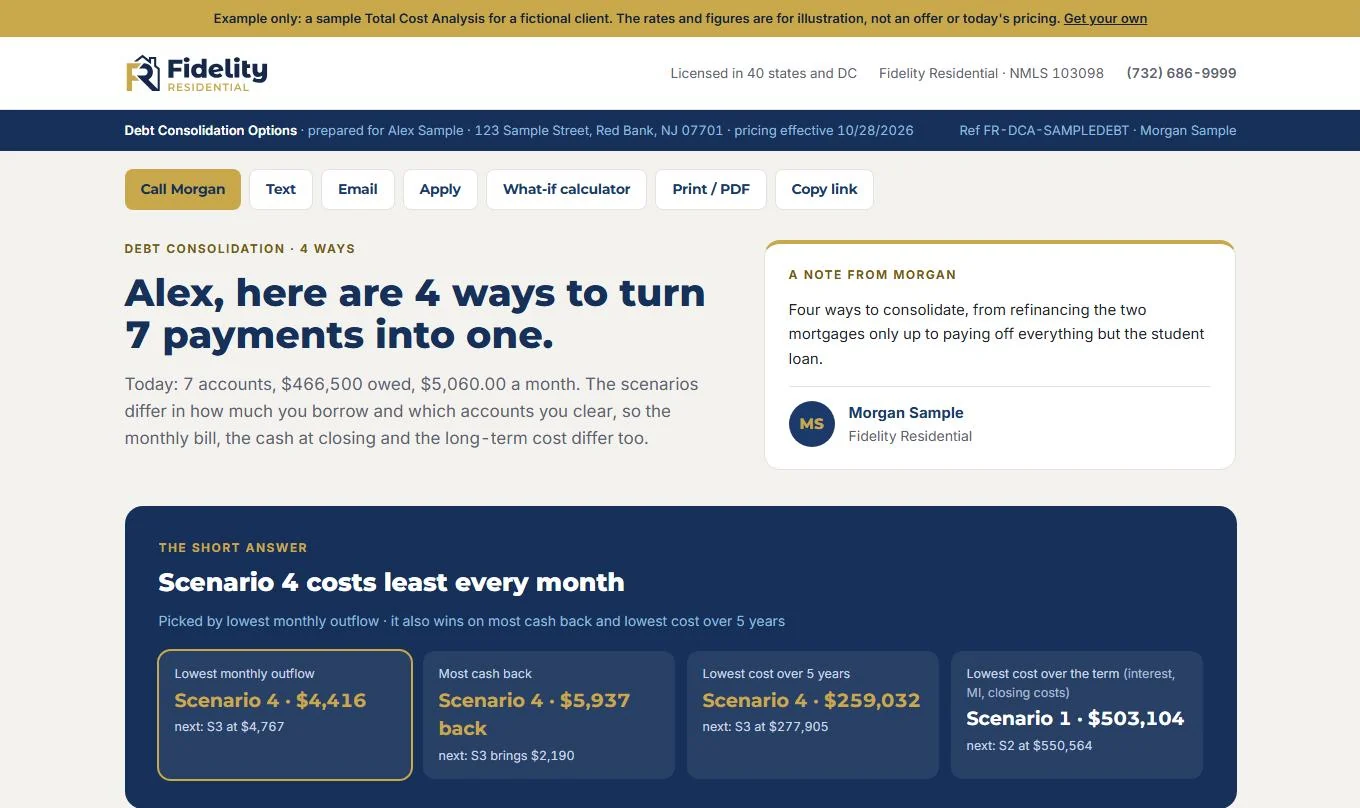
Which accounts each option pays off, what stays open, and the total you pay each month, at closing and over time.
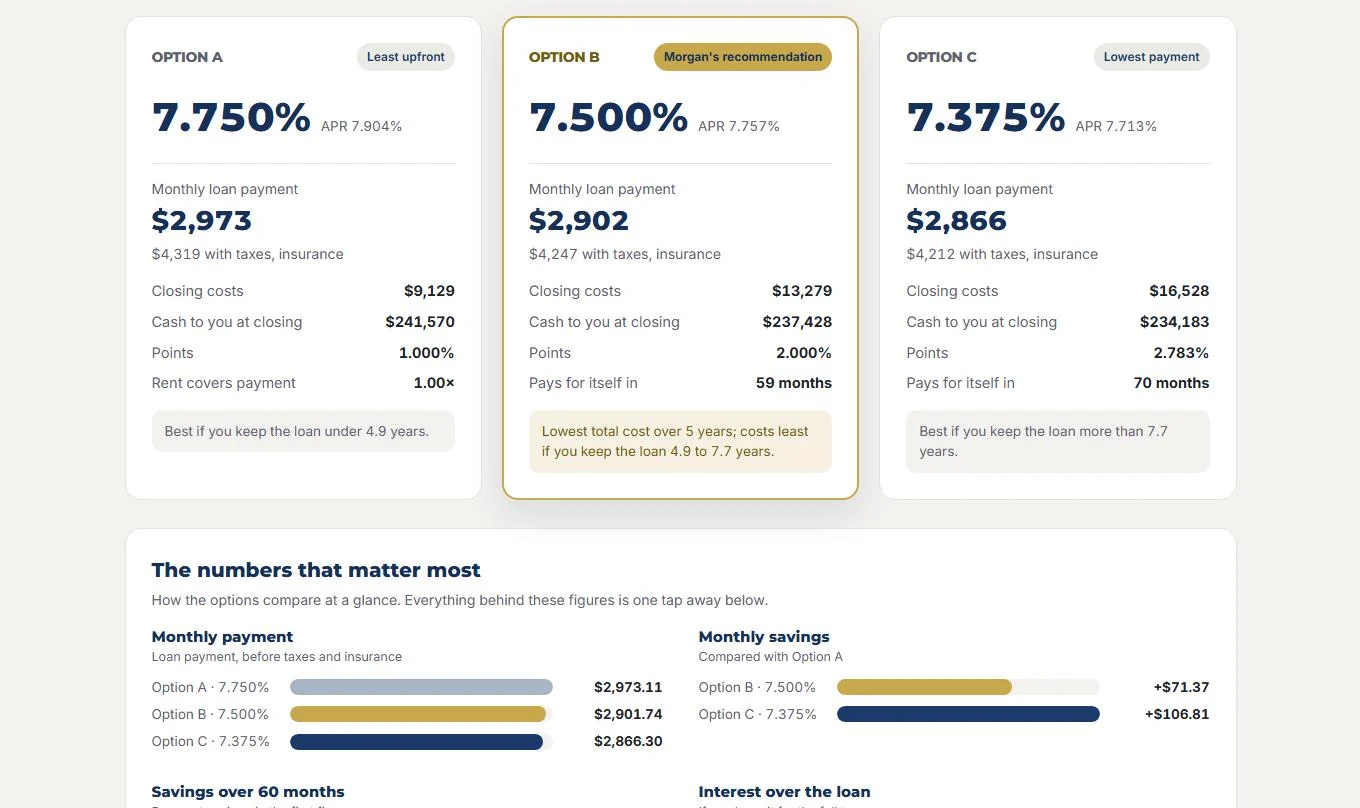
Pay more up front for a lower rate, or less up front for a higher one: the analysis shows how long each choice takes to pay for itself.
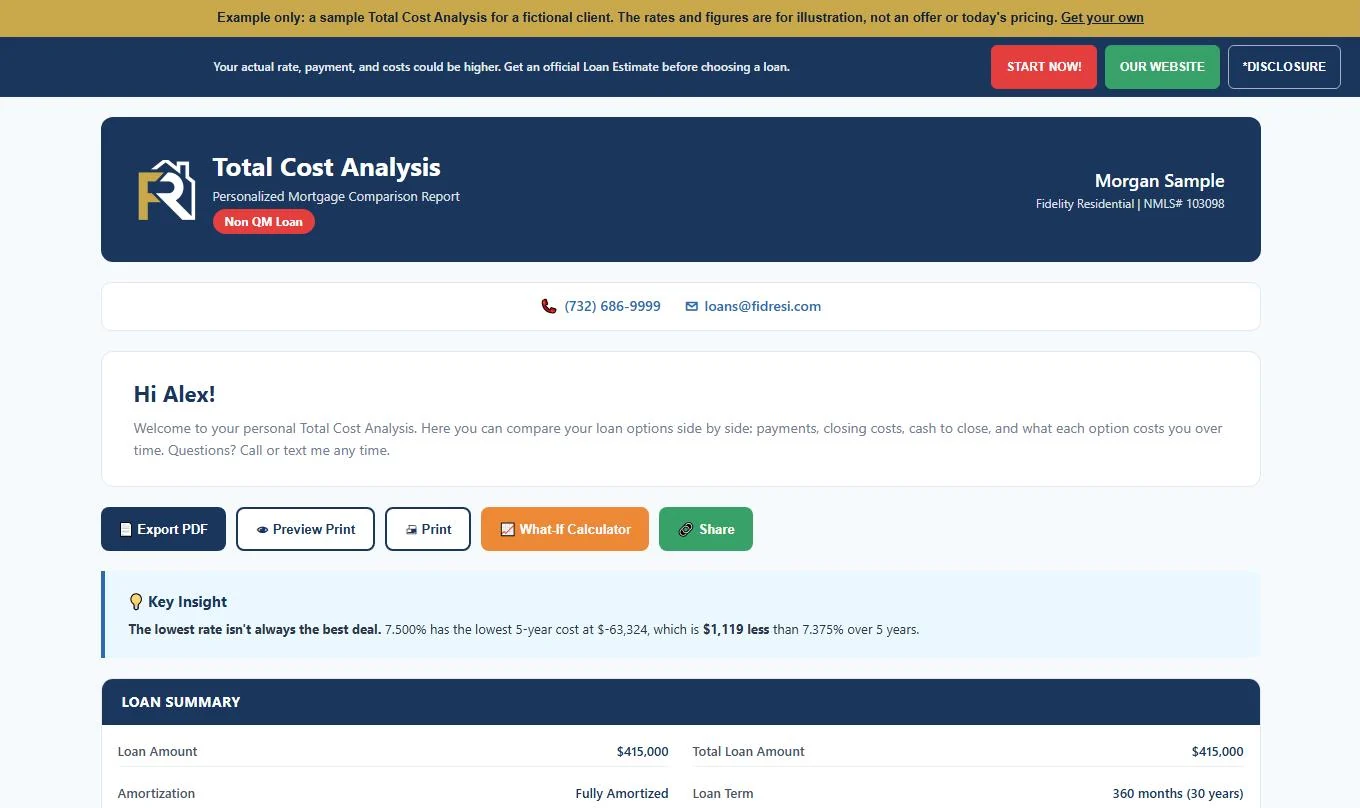
Some clients prefer our original one-column report. Your loan officer can send either.
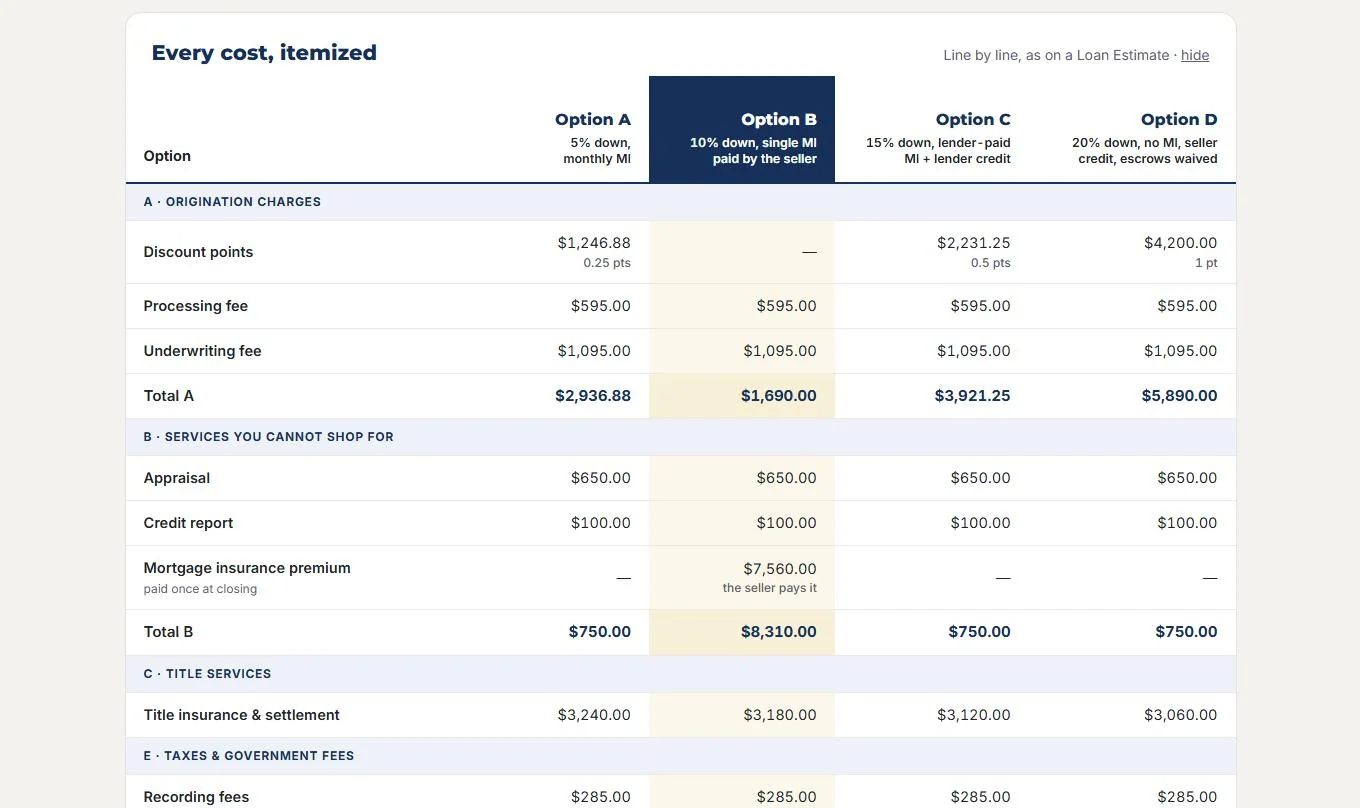
The totals are only the start. Each option lists its charges grouped the way your Loan Estimate will group them, so nothing is a surprise when the official disclosures arrive.
Many pre-approval letters are written from what a buyer says about their income and savings. Ours are not. Before we issue a letter, an underwriter reviews your credit report and documents your income and assets, and the loan is approved subject only to the property: the contract, the appraisal, title and insurance. The letter says exactly what was verified and on what date.
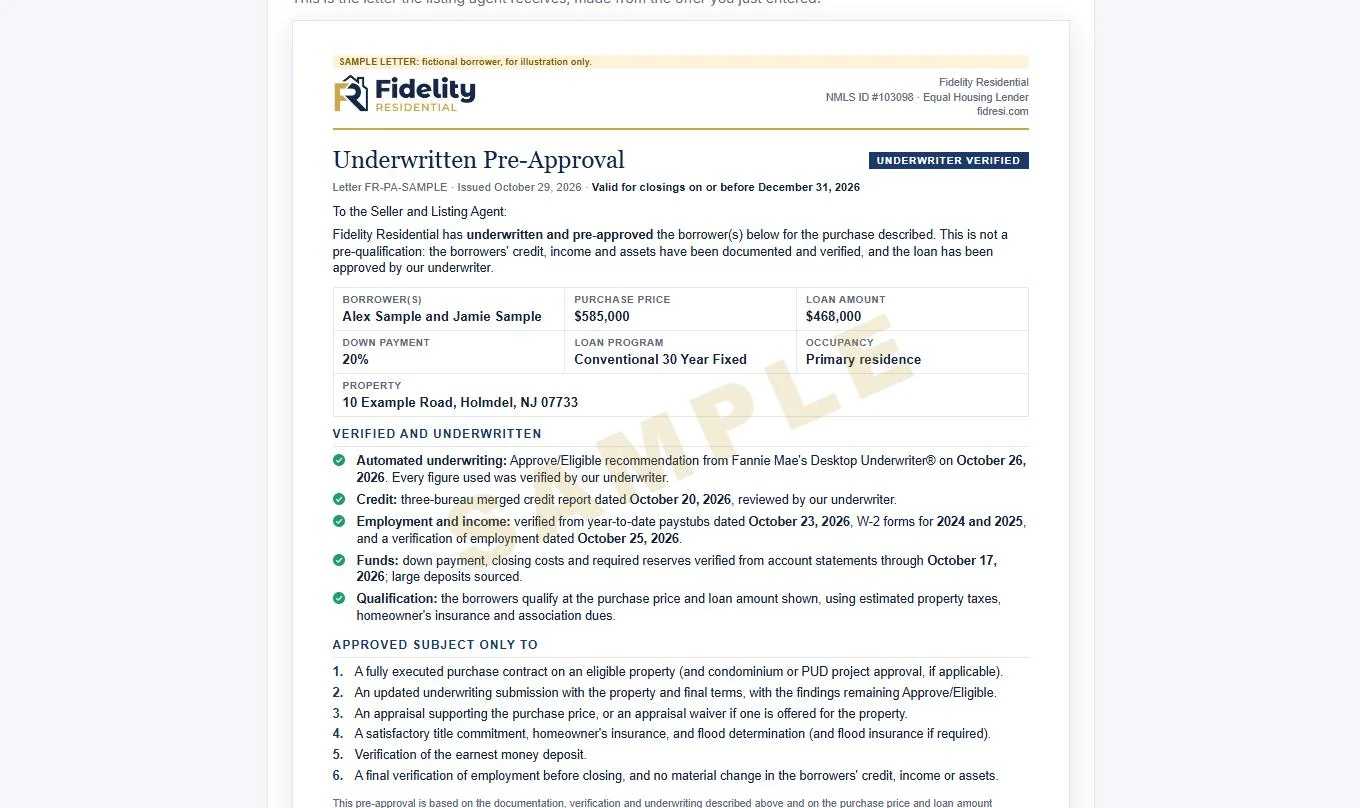
A seller choosing between offers wants the one most likely to close. A letter that shows verified credit, income and assets, and a check the listing agent can run in seconds, answers that question before it is asked.
The hard part of underwriting is already done, so the time between contract and closing goes to the property: the appraisal, title and insurance, not a first look at your paperwork.
Once your client is pre-approved, their buyer's agent can make a letter for each offer from our partner portal: the exact price, the exact address, ready at once, any day of the week. See how it works.
Real letter templates with fictional borrowers. Each program's letter lists what that program's underwriting verifies.
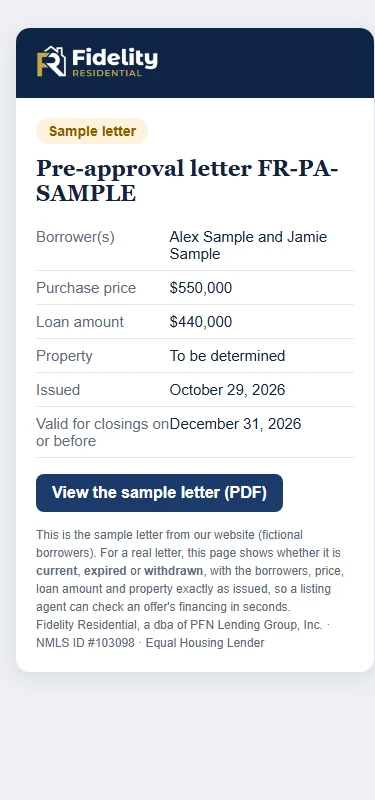
The verification page, fidresi.com/v/…
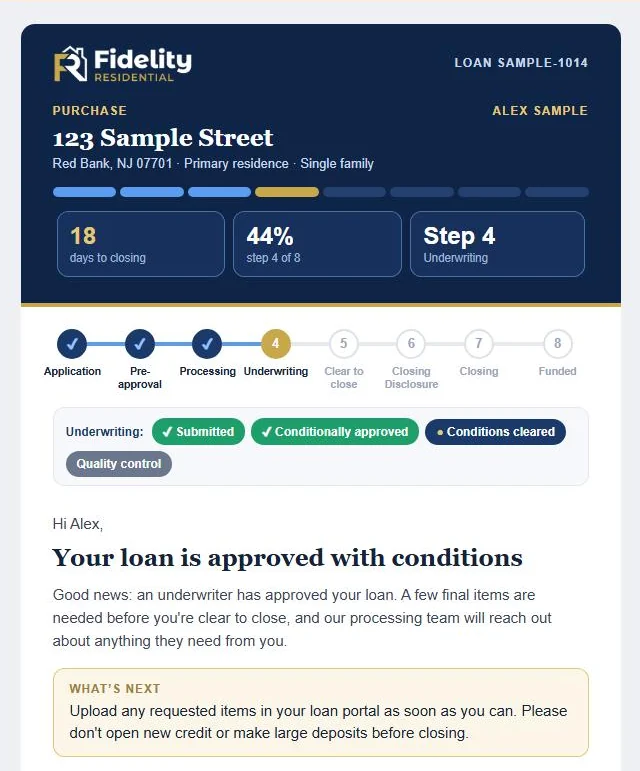
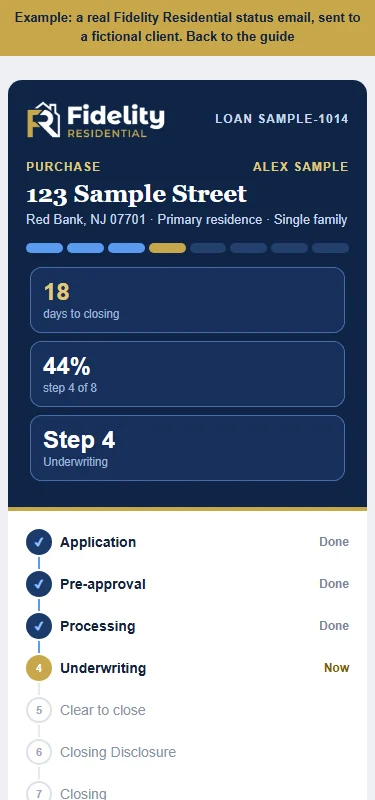
Each time your loan moves forward, from application to approval, clear to close and funding, you get an email that shows where the loan stands, what happens next and anything we need from you, along with a short text if you have agreed to texts. A co-borrower gets the same updates.
Fidelity Residential: Hi Alex, great news: your loan is approved with conditions. Please upload any requested items in your loan portal: fidresi.com/l/… Reply STOP to opt out.
Fidelity Residential: Hi Jordan, you're clear to close! We'll contact you shortly to schedule your closing. Reply STOP to opt out.
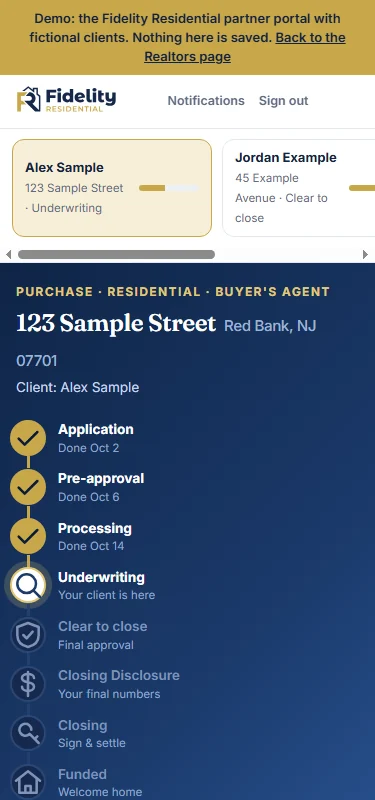
Your agent can have their own sign-in to our partner portal: every milestone and the closing date as it happens, plus an email or text when the loan moves. They see progress, not your finances: loan terms, documents and conditions stay private to you.
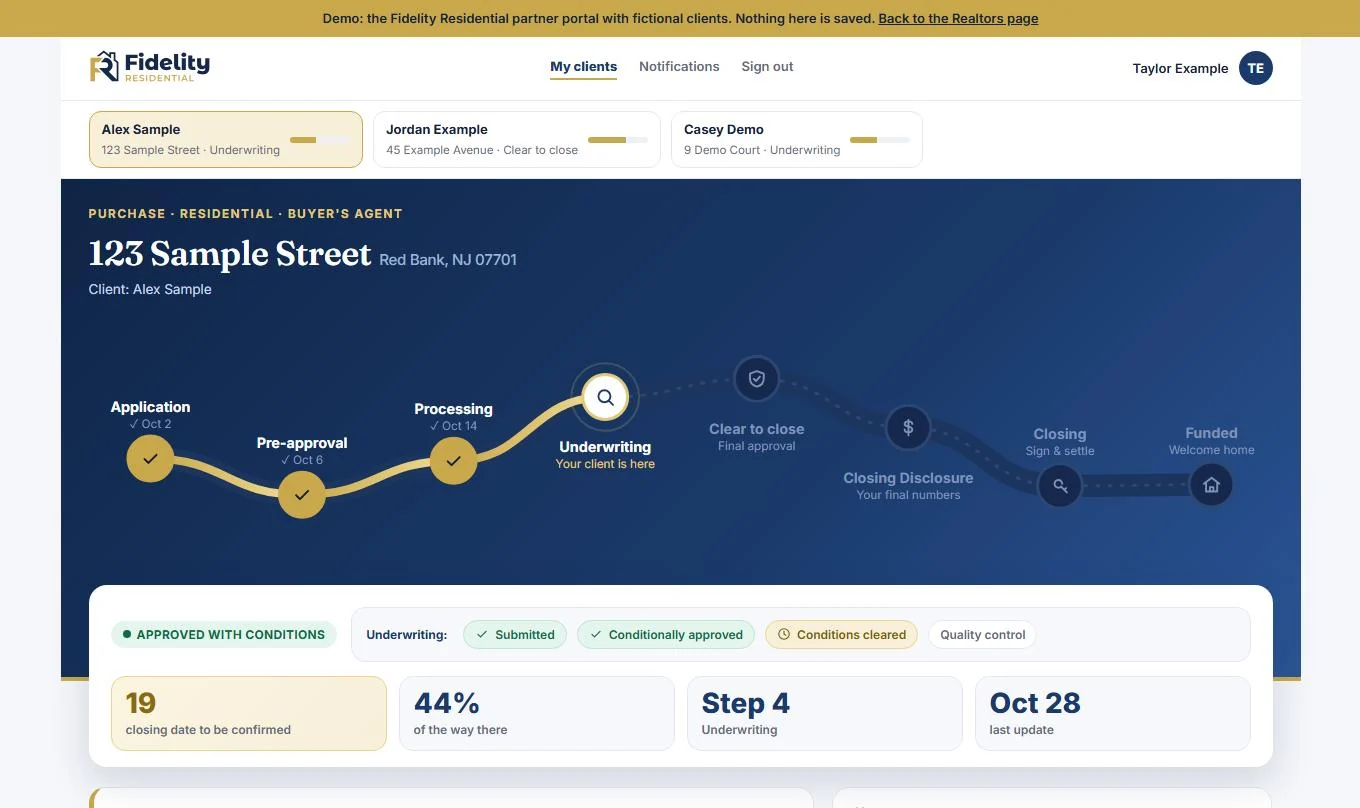
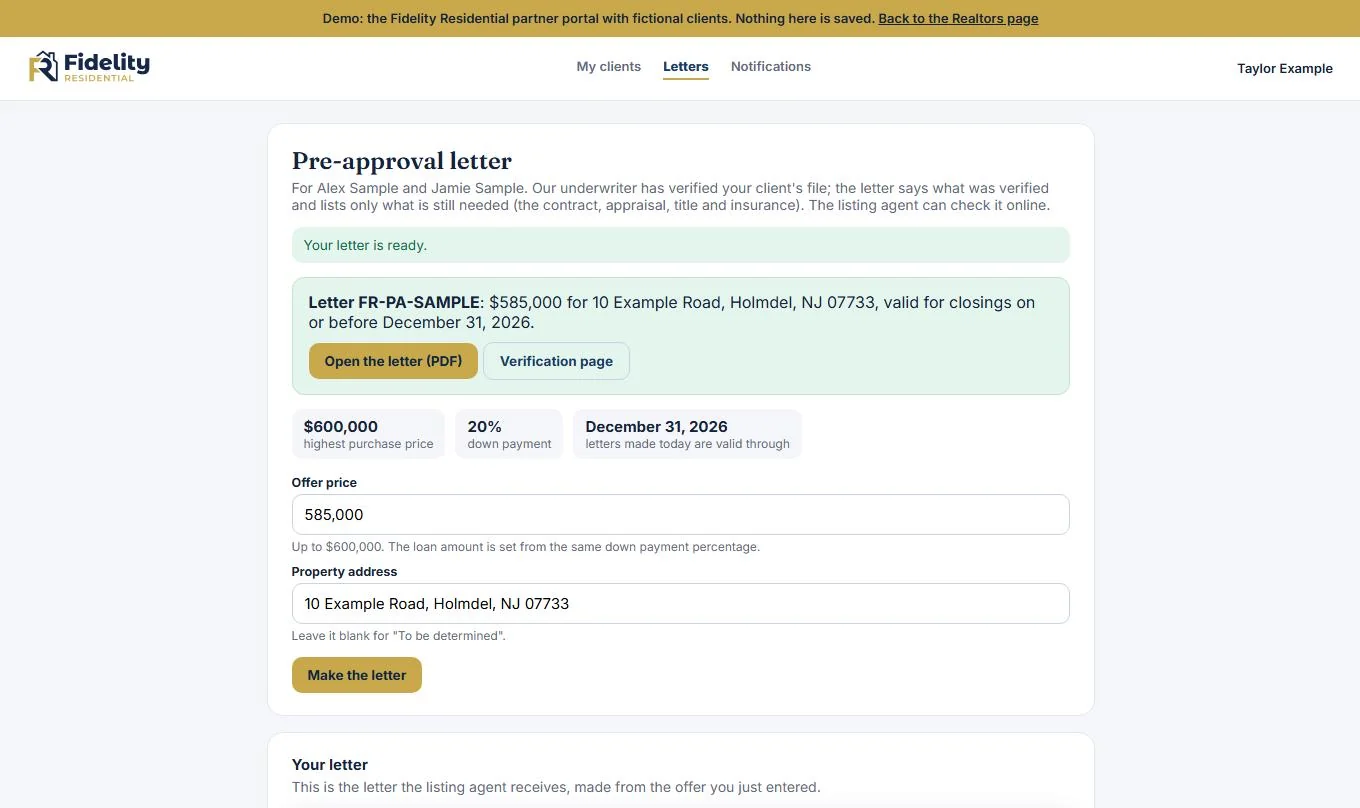
Once a client is pre-approved and agrees, their buyer's agent can make a letter for each offer straight from the portal. They enter the offer price, up to the approved amount, and the property address; the loan amount follows the same down payment, and the letter is ready to send at once. Every letter is numbered, checkable online, and recorded on the loan so the loan officer sees it.
Real estate agent? See how we work with agents.
About these examples: every client, address, loan officer and figure on this page and in the linked examples is fictional and for illustration only. The rates, payments and costs shown are not an offer of credit or today's pricing, and a pre-approval is not a commitment to lend on a specific property. Programs, terms and eligibility depend on credit, income, property and underwriting review and are subject to change without notice. Fidelity Residential is a dba of PFN Lending Group, Inc., NMLS #103098, an Equal Housing Lender.
It is the quote we send you: a personal web page that puts your loan options side by side, with the monthly payment, the closing costs, the cash you need at closing, and what each option costs over five years and over the life of the loan. It names the option we would choose and why, and itemizes every cost the way a Loan Estimate does. It is a quote, not an offer of credit. See the examples above.
A pre-qualification is based on what you tell a loan officer about your income and savings. Before we issue a pre-approval letter, an underwriter reviews your credit report and documents your income and assets, and the loan is approved subject only to the property: the contract, the appraisal, title and insurance. We issue letters only on files we underwrite ourselves, or that the investor's own underwriter has approved. A pre-approval is still not a commitment to lend on a specific property.
The borrowers, the price of the offer it goes with, the loan amount and the property, what the underwriter verified and on what date, and the short list of conditions left. It shows your offer price, never the most you could borrow, so the seller never sees your ceiling. No income, credit score, debt ratio or account balance appears on the letter.
Each letter says it is valid for closings on or before a set date. We set that date from the age of the documents we verified: 30 days before the oldest of them expires, and never more than 90 days after the letter is issued. On a conventional loan the date can be earlier, when a new year's W-2 or tax return would be needed.
Every letter is numbered. The listing agent can check it online, at fidresi.com/v/ followed by the letter's code, and see whether it is current, expired or withdrawn, with the borrowers, price, loan amount and property exactly as issued.
Yes, once you are pre-approved and agree. Your buyer's agent can make a letter for each offer from our partner portal: they enter the offer price, up to the approved amount, and the property address, and the loan amount follows the same down payment. The letter is ready at once, numbered, checkable online and recorded on your loan, so your loan officer sees it. See how it works.
Every milestone and the closing date as it happens, plus an email or text when the loan moves. Your agent sees progress, not your finances: loan terms, documents and conditions stay private to you.
Each time your loan moves forward, from application to approval, clear to close and funding, you get an email that shows where the loan stands, what happens next and anything we need from you, along with a short text if you have agreed to texts. A co-borrower gets the same updates.
Tell us about the loan you want and a licensed loan officer will send your Total Cost Analysis.
Last reviewed: